
Answers for both are below. Shoppers with questions about a loan, lease or payment should contact their lender.
Key takeaways
- LendPro is a financing platform that sends one shopper application to the retailer's chosen lenders, and it is not a lender.
- By default one application reaches several lenders at once, and a retailer may instead choose the traditional waterfall setting, configured by LendPro for each location.
- When a lender declines, the application is routed to another applicable lender, if one is available, and a shopper who wants a higher amount starts a new application.
- LendPro's go-live SLA is 10 business days, and timing depends on lender activation and integration scope.
Questions from retailers: the basics
What is LendPro?
LendPro is a multi-lender financing platform for retailers, the Financing Intelligence platform. One customer application reaches the lenders in your lineup, and shoppers can pre-qualify earlier in the shopping journey. LendPro is a technology layer, not a lender. The retailer chooses its lenders and routing setting, and LendPro configures the financing flow for each location. See Financing Intelligence.
Is LendPro a lender?
No. LendPro is not a lender, not a financial institution and not a buy now, pay later company. It is a technology platform that connects retailers, shoppers and 18+ lenders and 25+ lending programs. LendPro handles the application, routing and reporting; lenders make all credit decisions and set all terms.
What is embedded pre-qualification?
Embedded pre-qualification puts the financing check where shoppers are already deciding: product pages and cart, in-store kiosks and tablets, QR codes, text links and a hosted application launched from the POS. Not every provider offers a pre-qualification pathway. Learn more about embedded pre-qualification.
Does LendPro's pre-qualification affect a customer's credit score?
Where the provider supports pre-qualification, it uses a soft pull and won't affect credit scores. A lender may run a hard inquiry if the shopper accepts an offer and completes that lender's full application. A pre-qualified amount is subject to the lender's final approval and is not a guarantee of approval.
Can LendPro work in-store and online?
Yes. LendPro can run on your website, on in-store kiosks and tablets, through QR codes and text links, and from your POS. Configure financing for each sales channel. Online and in-store lender availability, application requirements, and results may differ. LendPro works with the retailer to establish the appropriate configuration for each channel. Where the configuration supports it, an associate can use Lookup Application to find an application a shopper started online. See kiosks and devices.
Questions from retailers: conversion and strategy
Why does pre-qualification earlier in the customer journey matter?
Shoppers who know their buying power before they reach the counter shop with more confidence, and fewer carts stall on a surprise financing step at checkout.
How does LendPro help increase conversion?
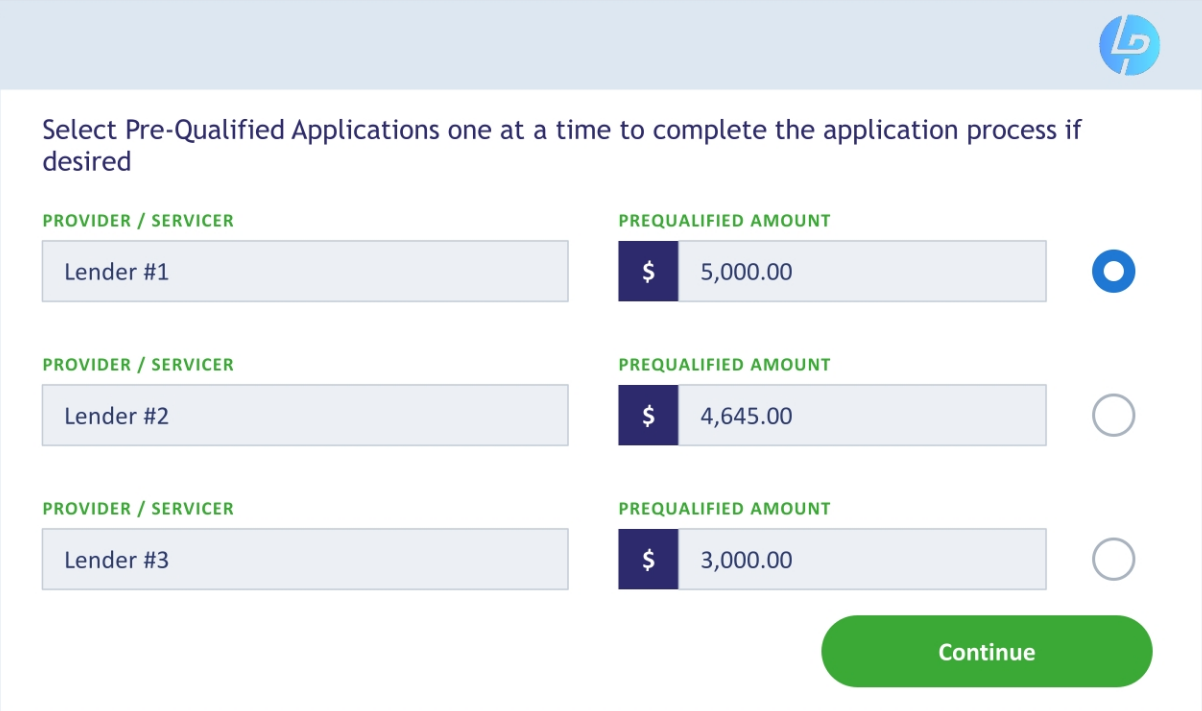
LendPro removes financing friction. Shoppers apply once and one application reaches the lenders in your lineup. By default, pre-qualified offers from more than one provider can show side by side. If a shopper is declined, the application is routed to another applicable lender, if one is available.
Does LendPro notify my store when a customer applies?
Yes. LendPro notifies the store when a customer applies, through any channel: your website or product pages, in store, a kiosk, a text link or a QR code. See store alerts and follow-up marketing.
How does LendPro help turn a pre-qualified shopper into a sale?
For 30 days after pre-qualification, LendPro offers marketing tools that help pre-qualified shoppers return to complete the lender's full application; the lender makes the final decision. They include re-engagement through SPLICE Software Data-Driven Dialogs (text, chat, call, email, voice) on behalf of the merchant that created the lead. A pre-qualified amount is subject to the lender's final approval.
Can LendPro bring back customers who applied before?
Yes. LendPro markets to customers who previously applied, inviting them to re-apply and re-purchase. This outreach happens with the shopper's consent; shoppers can opt out at any time (reply STOP to texts). A new application reaches the lenders in your lineup, and each lender makes its own decision.
What conversion lift can I expect from embedded financing?
LendPro does not promise a set lift. Results depend on your industry, your lender lineup, where you place entry points and how your team uses them. Your merchant portal's Daily Applications, Sales Performance and Approval Rates reports show what is happening in your stores so you can measure it yourself.
How does LendPro support AI-driven and agentic commerce?
LendPro provides the financing layer for real-time commerce, so buying power is available while a product is being considered rather than at a separate checkout step. LendPro's view is that agentic commerce creates intent, and conversion depends on financing intelligence. See agentic commerce.
Questions from retailers: lenders and routing
What is a retailer-controlled waterfall?
It is a financing waterfall whose lender order reflects the retailer's choices rather than a lender's. The retailer chooses which lenders it wants and its routing setting, and LendPro configures the flow for each location. Changes are requested through LendPro and can be limited by lender agreements and program requirements. See retailer-controlled waterfall. This outreach happens with the shopper's consent; shoppers can opt out at any time (reply STOP to texts).
How does LendPro route an application?
By default, LendPro sends one application to multiple lenders at once, and pre-qualified offers from more than one provider can show side by side. A retailer may instead choose the traditional waterfall setting: prime first, then near prime offers if prime declines, then No Credit Needed. Either way, when the store offers it, shoppers can choose No Credit Needed at the start, which skips the primary lenders. LendPro uses a financing flow configured for each location based on the lenders assigned to that location and the requirements of those programs. Contact LendPro to review configuration changes. See waterfall financing.
What happens if a customer is declined by one lender?
The application is routed to another applicable lender in your lineup, if one is available. The waterfall does not keep running after an approval: a shopper who wants a higher amount starts a new application. See second-look financing.
How is LendPro different from single-lender buy now, pay later?
A single-lender program checks one lender, and that lender's criteria decide the outcome. With LendPro, one application reaches the lenders configured for the store across prime, near prime and No Credit Needed, from LendPro's network of 18+ lenders and 25+ lending programs. Each lender sets its own criteria; availability varies by retailer, state and purchase.
Why should a retailer use LendPro if they already offer buy now, pay later?
A buy now, pay later program is usually one option for one slice of credit. With LendPro, one application can reach several lenders, and your existing providers can sit inside your lineup if they are in the LendPro network.
Does LendPro replace my current financing providers?
No. LendPro works alongside them. Many retailers keep their current prime lender first and add near prime and No Credit Needed providers behind it, so existing financing relationships stay in place.
How is LendPro different from financing marketplaces?
With LendPro, the retailer chooses its lender lineup and routing setting, configured by LendPro for each location, and keeps the store's customer flow. Marketplaces often control the customer experience themselves. LendPro can also re-engage pre-qualified shoppers on behalf of the merchant that created the lead through SPLICE Software Data-Driven Dialogs (text, chat, call, email, voice), part of LendPro's 30-day follow-up marketing.
We will walk through your lenders, tiers and entry points in a live demo.
Questions from retailers: setup, reporting and fit
How fast can I launch LendPro?
LendPro's go-live SLA is 10 business days. Timing depends on lender activation and integration scope, and custom integrations take longer. LendPro confirms the start date and prerequisites during onboarding. LendPro can launch a hosted application from your POS through the Launch API; ask which systems are supported today. Additional integration options may be available for specific needs. Discuss your workflow, required data, and implementation requirements with LendPro during an integration call. STORIS retailers can use LendPro 2.0 inside STORIS ERP and NextGen. See integrations.
Does LendPro charge extra to build AEO financing pages?
No. LendPro builds complete AEO financing pages for its retailers, written so AI assistants and search engines can read them, at no additional cost. They are included in the LendPro subscription fee. See AEO financing pages and product-page financing.
Can LendPro add financing to my product pages?
Yes. LendPro helps retailers add a See If You Pre-Qualify button, payment estimates and "as low as" monthly payments on product cards, linked to the store's LendPro application. Abdul Furniture in Corona, NY is an example: "See your payment estimate" and "As low as $29.10/mo"* on product cards, plus a dedicated financing page. See AEO financing pages and product-page financing.
*Example only. Payment estimates are examples only; lenders set APR, term and payment based on approval.
Does LendPro work for small businesses or just enterprise retailers?
Both. LendPro works with single-location independents and multi-location chains. See LendPro partners.
What industries does LendPro support?
Home furnishings, mattresses, appliances, HVAC, home improvement, medical and dental, mobile and personal electronics, automotive service and tires, and jewelry. LendPro works with each retailer on a lender mix that fits its industry. See furniture, tire and auto service, jewelry and medical and dental.
What reporting do retailers get?
The merchant portal has a Dashboard, Search, Orders and three reports: Daily Applications (by location, associate and initial lender), Sales Performance (by store, associate and customer) and Approval Rates (lenders side by side), with export to CSV. Associate-level results show when Employee Tracking is turned on.
Can we finalize sales and handle returns in LendPro?
Yes. In the LendPro portal, which connects to STORIS for STORIS retailers, merchants can apply, finalize the sale, transact and process returns and exchanges in one place, without logging into each lender's portal. Cancel and refund in the portal is available for most lenders in the network; a few providers still require the provider's portal for cancellations and refunds. See STORIS.
Is shopper data secure?
LendPro holds a SOC 2 report, and shopper data is encrypted in transit. Application data is shared with the lenders reviewing the application and with service providers that process it under LendPro's privacy notice. Qualified prospects can request LendPro's security documentation through their LendPro representative. See security.
Still have questions?
Retailers: request a demo for a walkthrough of how LendPro fits your stores, or email merchant support at support@mylendpro.com. Shoppers: for questions about an offer, an agreement or a payment, contact your lender; LendPro is not a lender. For anything else, email info@mylendpro.com or call (434) 202-0137, or see contact LendPro.
Pre-qualified amounts are subject to the lender's final approval. Not all providers offer pre-qualification. Lenders make all credit decisions and set all terms; availability varies by retailer, state and purchase. Lease-to-own is a rental-purchase agreement, not a loan. Total cost is higher than the cash price.
Are you a shopper?
Shopper questions about credit, applying, texts and accounts are answered on the shopper FAQ. Shoppers can search participating stores by ZIP code with Find a store.
Frequently asked questions
Is LendPro a lender?
No. LendPro is not a lender, not a financial institution and not a buy now, pay later company. It is a technology platform that connects retailers, shoppers and 18+ lenders and 25+ lending programs. LendPro handles the application, routing and reporting; lenders make all credit decisions and set all terms.
How does LendPro route an application?
By default, LendPro sends one application to multiple lenders at once, and pre-qualified offers from more than one provider can show side by side. A retailer may instead choose the traditional waterfall setting: prime first, then near prime offers if prime declines, then No Credit Needed. Either way, when the store offers it, shoppers can choose No Credit Needed at the start, which skips the primary lenders.
What happens if a customer is declined by one lender?
The application is routed to another applicable lender in your lineup, if one is available. The waterfall does not keep running after an approval: a shopper who wants a higher amount starts a new application.
Does LendPro notify my store when a customer applies?
Yes. LendPro notifies the store when a customer applies, through any channel: your website or product pages, in store, a kiosk, a text link or a QR code.
How fast can I launch LendPro?
LendPro's go-live SLA is 10 business days; timing depends on lender activation and integration scope, and LendPro confirms the start date during onboarding. STORIS retailers can use LendPro 2.0 inside STORIS ERP and NextGen.
Does LendPro charge extra to build AEO financing pages?
No. LendPro builds complete AEO financing pages for its retailers, written so AI assistants and search engines can read them, at no additional cost. They are included in the LendPro subscription fee.
Can LendPro add financing to my product pages?
Yes. LendPro helps retailers add a See If You Pre-Qualify button, payment estimates and "as low as" monthly payments on product cards, linked to the store's LendPro application. Abdul Furniture in Corona, NY (abdulfurniture.com) is an example, with "As low as" payments on product cards and a dedicated financing page. Payment estimates are examples only; lenders set APR, term and payment based on approval.
What industries does LendPro support?
Home furnishings, mattresses, appliances, HVAC, home improvement, medical and dental, mobile and personal electronics, automotive service and tires, and jewelry. LendPro works with each retailer on a lender mix that fits its industry.
Does applying for LendPro financing hurt my credit score?
Where the provider supports pre-qualification, checking whether you pre-qualify uses a soft pull and won't affect your credit score. If you choose an offer and complete that lender's full application, the lender may run a hard inquiry. Some providers do not offer pre-qualification, and the No Credit Needed providers' full applications may include a check with the credit bureaus and/or alternative credit sources.
How do I find an application I already started?
Choose Lookup Application on the store's financing page, kiosk or link, and enter the details it asks for. It returns the application you already started, so you do not begin again. In the store, an associate can also find it with Lookup Application.
How do I refer a store to LendPro?
Shoppers can email the store's name and location to info@mylendpro.com. A store that wants to offer LendPro financing can email support@mylendpro.com.