
The retail financing platform for every credit tier
LendPro is a retail financing platform that connects your shoppers with multiple lenders through one application. Furniture, tire, jewelry and other retailers use it at thousands of merchant locations so more shoppers get a path to buy, from prime to No Credit Needed.
Modular sectional sofa · $3,850 · one application, soft pull where supported
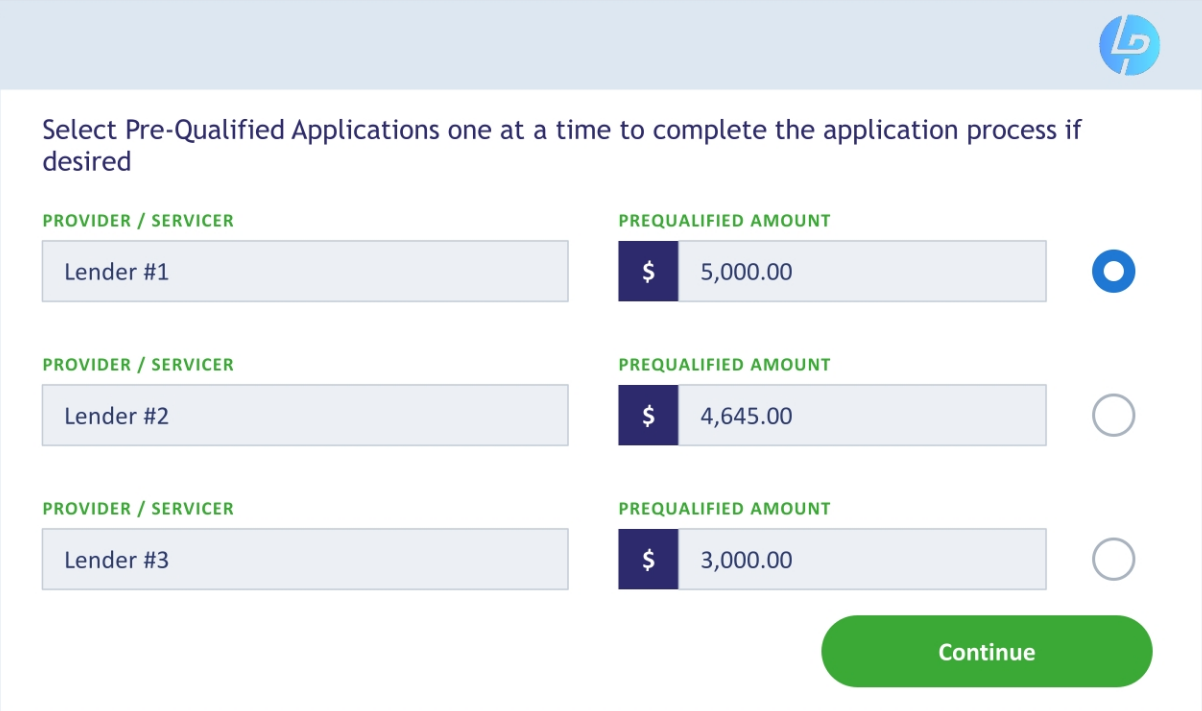
You pre-qualified with 3 providers
- Provider AInstallment loanUp to $5,000
- Provider BInstallment loanUp to $4,645
- Provider CLease-to-ownUp to $3,000
One application reaches several lenders at once. The shopper picks an offer to continue.
Lenders review in the configured order
- 1PrimeBank programDeclined
- 2SecondaryNear prime lenderPre-qualified up to $4,000
- 3No Credit NeededShown next if neededNot needed
Prime first. If prime declines, secondary offers show next, then No Credit Needed.
Prefer No Credit Needed? Shoppers can choose it at the start and compare offers side by side.
Illustrative example. Pre-qualified amounts are subject to each provider's final approval. *Not all providers offer a pre-qualification pathway. Lease-to-own is a rental-purchase agreement, not a loan.
- 18+lenders
- 25+lending programs
- Primeto No Credit Needed
- 1application
- 10business day go-live SLA
Trusted by thousands of merchant locationsFurniture, tire, jewelry and more, plus retailers that sell online. See partners





What retailers say
"A white-glove partner from day one."
Lee NelsonAssistant Controller, American Furniture Warehouse"LendPro has made a positive impact on the financing process at our store. We are now able to cater to a larger demographic and increase our bottom line."
Sarah PeltonStore Manager, Bernie & Phyl's Furniture"LendPro has been a great partner. The application is easy for the customer, and the response is very fast."
Sabrina BoothEurocare Missouri City
Customer experiences. Results vary by retailer, lenders and shoppers.
How it works
One application. Every lender you choose.
One application reaches the lenders configured for your location, at once or in a waterfall order, so one decline does not have to end the sale.
- 01Apply once
One application from a product page, QR code, text link or in-store device, with a soft pull where the provider supports pre-qualification.
- 02Lenders review
Several lenders review at once, or in a waterfall order configured for your location: prime, then secondary, then No Credit Needed.
- 03Shopper picks an offer
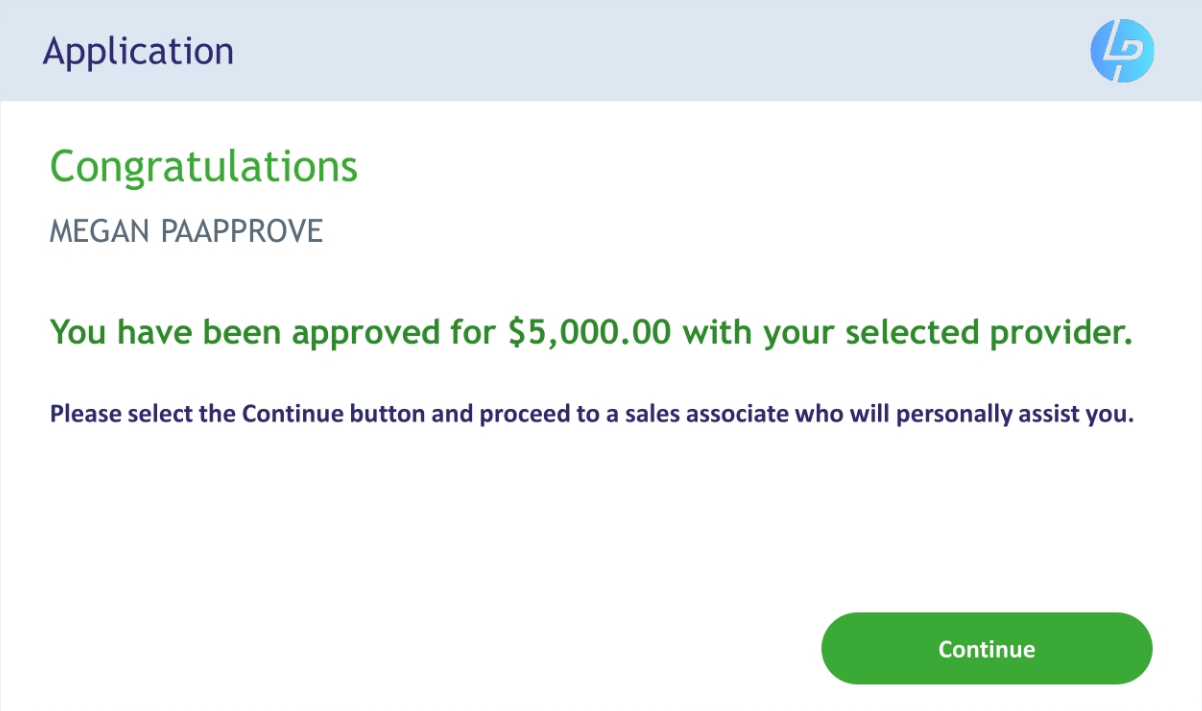
Pre-qualified offers show to the shopper, who picks one and continues with that lender.
- 04You close and report
The lender funds the purchase. Reports break out results by lender, store and associate.
The full flow, step by step
- Put financing where shoppers decide. Pre-qualification sits on product pages and the cart, on in-store kiosks and tablets, behind QR codes and text links, and inside a hosted application launched from your POS.
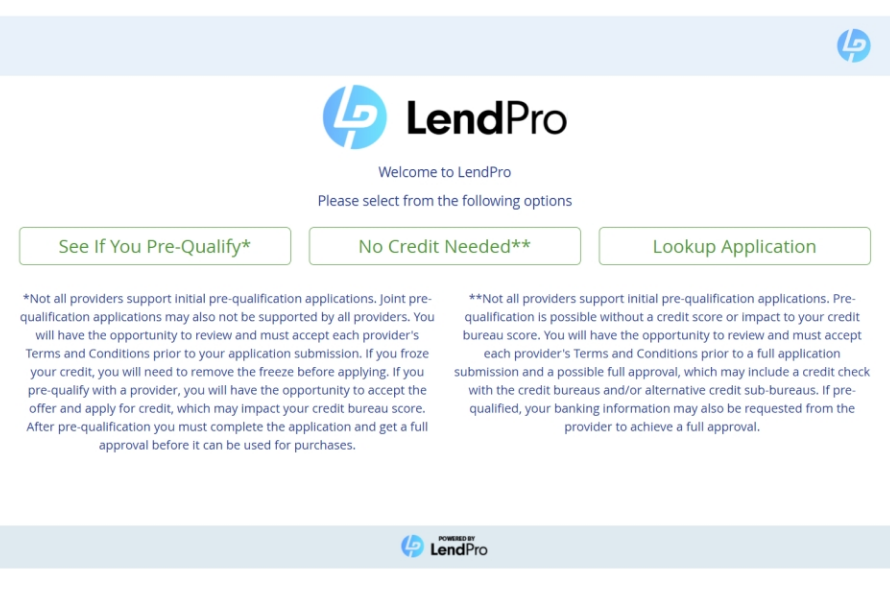
- The shopper picks a path. See If You Pre-Qualify, No Credit Needed when the store offers it, or Lookup Application to return to an application already started. Where the provider supports pre-qualification, it uses a soft pull and won't affect credit scores. A lender may run a hard inquiry if the shopper accepts an offer. Not all providers offer a pre-qualification pathway.
- The application follows your location's configured flow. LendPro uses a financing flow configured for each location based on the lenders assigned to that location and the requirements of those programs. Contact LendPro to review configuration changes. By default, one application goes to several lenders at once, and pre-qualified offers from more than one provider show side by side. Or choose the traditional waterfall setting: prime first, then secondary (near prime) offers if prime declines, then No Credit Needed. Either way, a shopper who chooses No Credit Needed at the start skips the primary lenders and goes straight to no-credit-needed providers, where several offers may show side by side.
- The shopper selects an offer and completes that provider's application. The provider's confirmation shows the available limit. The full application may ask for employment, debit card or bank details. The shopper agrees to the provider's terms and submits.
- You finalize the sale and read the results. In LendPro, the store enters the invoice, the customer e-signs in store or by text or email link, and the store processes settlement on delivery. Reports break out applications and approvals by location, lender and associate, with Employee Tracking on.
Pre-qualified amounts are subject to the lender's final approval. How waterfall financing works.
The product
What your shopper sees, and what your team sees
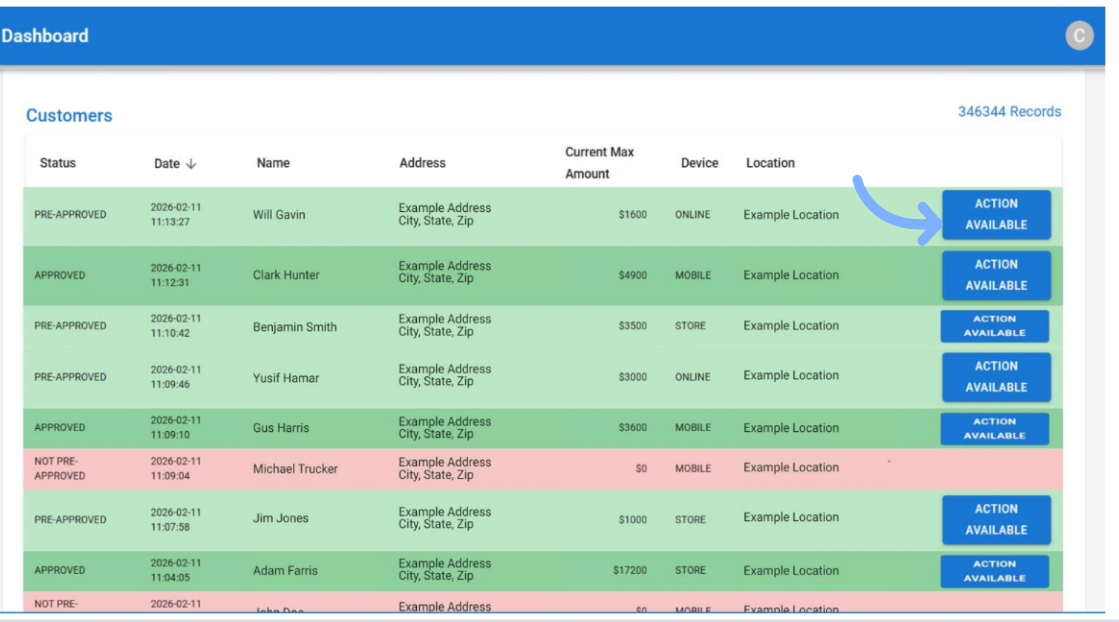
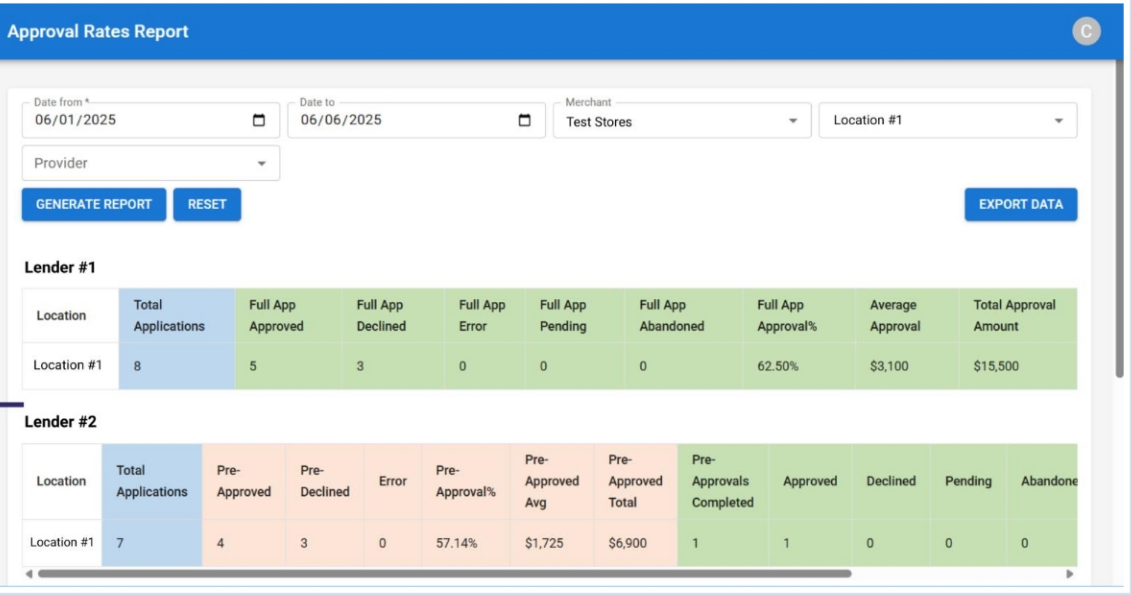
One application from a product page, QR code, text link or in-store device, and one merchant portal for every result. Screens are from the live LendPro application.
- Send Links. Text or email an application link from the portal.
- Promotions. Web banners, pre-qual buttons, QR codes and store signage.
- Finalize and settle. Invoice, e-sign, and process settlement on delivery.
- Reports. Applications, sales and approval rates by location, associate and lender.
Where the provider supports pre-qualification, it uses a soft pull and won't affect credit scores. A lender may run a hard inquiry if the shopper accepts an offer. Pre-qualification is not a guarantee of approval. Lease-to-own is a rental-purchase agreement, not a loan. Total cost is higher than the cash price.
After they apply, LendPro keeps working the sale
- Every channelYour store is notifiedLendPro notifies your store whenever a shopper applies through the channels you offer: website, product page, in store, kiosk, text link, QR code or the store finder.How it works
- 30 daysBack to finish the applicationFor 30 days after pre-qualification, LendPro marketing tools help shoppers return to complete the lender's full application, with consent. The lender decides.How it works
- Past applicantsRe-apply and re-purchaseWith consent, LendPro markets to customers who applied before, inviting them back to re-apply and buy again. Shoppers can opt out at any time.How it works
Lending programs
18+ lenders and 25+ lending programs, configured for each location
Many lenders offer more than one program. You choose the lenders you want and whether they review at once or in a waterfall order, and LendPro configures the flow for each location.
PrimeStrong credit
- Bank installment loans
- Retail credit cards
- Promotional and deferred-interest plans
Near primeFair credit
- Installment loans
- Second-look credit cards
- Fixed monthly payment plans
Subprime and No Credit NeededLimited or rebuilding credit
- Installment loans for limited credit
- Lease-to-own (rental-purchase)
- No Credit Needed programs
Card processing: LendPro is a partner of Elavon, a merchant processing provider. Lineups vary by retailer and state; ask for the current lender lineup in a demo. Each lender sets its own criteria and terms. Availability varies by retailer, state and purchase. How waterfall financing works.
Decline cost calculator
What declines cost your store
Enter your own numbers. This estimates the sales that walk out when one lender says no, and what might be recovered at the rate you assume.
Illustrative estimate based only on the numbers you enter. It is not a LendPro performance claim and does not measure incremental revenue, profit or ROI, which also depend on purchase conversion, merchant costs and margin. Actual results depend on your lenders, shoppers and configuration.
Get your real numbers in a demoIntegrations
Which systems does LendPro work inside?
Financing works best when associates stay on the screen they sell from.
- STORIS. LendPro 2.0 is embedded in STORIS ERP and NextGen for furniture and appliance retailers. In the latest integration, associates apply, finalize, transact and process returns and exchanges in one LendPro portal, without logging into each lender's portal (cancel and refund are available for most lenders in the network; a few providers still require the provider's portal for cancellations and refunds). eSTORIS is planned. LendPro for STORIS.
- 1stMILE. LendPro's multi-lender platform sits behind 1stMILE's automated credit matching for auto service, tire and repair shops. In auto service, Midas is a LendPro partner, alongside AAMCO franchisees. LendPro for 1stMILE.
- APIs. Launch, POS Sync and Settlement APIs for platforms and custom systems. Developers.
LendPro's go-live SLA is 10 business days. Timing depends on lender activation and integration scope, and custom integrations take longer. LendPro confirms the start date and prerequisites during onboarding.
Additional integration options may be available for specific needs. Discuss your workflow, required data, and implementation requirements with LendPro during an integration call. All integrations.
Industries
Multi-lender financing, built for your vertical
One application, set up for how each kind of retailer sells.
- Home furnishingsSectionals, bedroom sets and whole-room packages, online and on the sales floor.
- MattressShow a payment on every bed and pre-qualify shoppers in one visit.
- ApplianceUrgent replacements and planned upgrades, financed at the counter or online.
- Home improvement and HVACLarger projects, in-home sales and longer terms.
- Tires, wheels and auto repairTurn deferred repairs into approved work orders, at the counter or by text.
- JewelryEngagement rings and fine jewelry, with private pre-qualification at the counter.
- Medical and dentalMore ways for patients to pay for treatment, through one application.
- Mobile and personal electronicsPhones, computers and electronics, in store and online.
Where financing shows up, by industry
| Industry | What shoppers finance | Where financing shows up |
|---|---|---|
| Furniture stores | Sectionals, bedroom sets, whole-room packages | Product pages, sales floor tablets, inside STORIS |
| Mattress stores | Mattresses, adjustable bases | Product pages, in-store kiosks |
| Appliance stores | Urgent replacements, kitchen packages | Product pages, POS, text links |
| Tire and auto service | Tires, brakes, transmissions, major repairs | Counter, text, QR code, 1stMILE checkout |
| Jewelry stores | Engagement rings, fine jewelry, watches | Product pages, private counter tablets |
| Medical and dental | Elective treatment and procedures | Front desk, text links |
| Mobile and electronics | Phones, computers, gaming | Product pages, kiosks |
Security and trust
Built for the data you are trusted with
- SOC 2 reportLendPro holds a SOC 2 report.
- Encrypted dataApplication data is sent encrypted.
- Soft-pull pre-qualificationWhere the provider supports pre-qualification, checking offers won't affect credit scores.
- Platform, not a lenderLenders make every credit decision and set every term.
Why LendPro
Why retailers choose LendPro
Why is one lender not enough?
Every lender approves a different slice of shoppers. A bank program may approve your strongest customers and decline the rest. When that happens at the counter, the associate either gives up, or opens a second portal and asks the shopper to start over. Both cost sales.
With LendPro, one application reaches the lenders in your lineup, either several at once or in the traditional waterfall order configured for your location. If a shopper is declined, the application is routed to another applicable lender, if one is available. A shopper who wants a higher amount after an approval starts a new application.
| Moment | One lender | LendPro default | LendPro traditional waterfall setting |
|---|---|---|---|
| Shopper uses See If You Pre-Qualify for a $2,400 mattress and base | One lender reviews | Several lenders in your lineup review at once | Your prime lender reviews first |
| Prime lender declines | Sale stalls or the shopper leaves | Pre-qualified offers from other lenders can still show side by side | Secondary (near prime) lenders review next |
| Secondary lender pre-qualifies $1,500 | Not reached | Shown next to any other offers; the shopper picks one | Secondary offer shown; No Credit Needed follows if secondary declines |
| Shopper chooses No Credit Needed at the start | Often not offered | Skips primary lenders; No Credit Needed offers may show side by side | Same: skips primary lenders |
Illustrative example. Pre-qualified amounts are subject to each lender's final approval. Amounts and terms are set by each lender. Lease-to-own is a rental-purchase agreement, not a loan. Total cost is higher than the cash price.
What does the retailer decide?
| Decision | Who makes it with LendPro |
|---|---|
| Which lenders you want in your lineup | You, the retailer, from the lenders available for your locations |
| Routing setting: several lenders at once, or the traditional waterfall order | You choose it, and LendPro configures the flow for each location |
| Changes to lenders or routing | You request them through LendPro; lender agreements and program requirements can limit them |
| Reviewing results and reporting | You, working with LendPro to manage the configuration |
| Whether a shopper is approved, and on what terms | Each lender |
| Which offer the shopper accepts | The shopper |
LendPro is not a lender. Lenders make all credit decisions and set all terms. Read how the waterfall setting works.
Is your financing ready for AI shopping?
Shoppers now start purchases by asking AI assistants what to buy and how to pay for it. If your financing is buried in a checkout pop-up, the assistant cannot see it. State your financing options plainly on your site, and keep a pre-qualification link one click away.
AI shopping can bring a shopper to the purchase decision, and the financing step still has to be clear for that shopper to finish.
Keep reading
From the LendPro blog
- CEO's Blog · March 2026Agentic Commerce Financing: The Data, Infrastructure, and Strategy Powering the Future of RetailRead
- CEO's Blog · January 2026Agentic Commerce Creates Intent. Conversion Depends on Financing Intelligence.Read
- Press release · August 2026LendPro and 1stMILE Partner to Expand Financing Access for Automotive AftermarketRead
- CEO's Blog · May 2025Why LendPro Is the Best Waterfall Finance Platform for RetailersRead
FAQ
Questions retailers ask
Straight answers about the platform, your lenders and your shoppers. See all FAQs.
What is LendPro?
LendPro is a SaaS financing orchestration platform, the Financing Intelligence platform for retailers. One application reaches the lenders configured for each store, from LendPro's network of 18+ lenders and 25+ lending programs. By default it goes to several lenders at once, or the retailer can choose the traditional waterfall setting, and LendPro configures the flow for each location.
Is LendPro a lender?
No. LendPro is not a lender. Lenders make all credit decisions and set all terms. LendPro is the software that routes the application.
Will checking financing options hurt a shopper's credit?
Where the provider supports pre-qualification, it uses a soft pull and won't affect credit scores. A lender may run a hard inquiry if the shopper accepts an offer.
Can I keep my current financing provider?
Yes. Many retailers keep their current prime lender and add near prime and No Credit Needed providers to their lineup.
What does the shopper see after applying?
By default, pre-qualified offers from more than one provider can show side by side, and the shopper picks one. With the traditional waterfall setting, the prime offer comes first, then secondary offers after a decline, then No Credit Needed. Pre-qualified amounts are subject to the lender's final approval.
What does a retailer see in reporting?
Applications appear in the merchant portal Dashboard, Search and Orders, alongside three reports: Daily Applications (by location, associate and initial lender), Sales Performance (by store, associate and customer) and Approval Rates (lenders side by side, with pre-qual and full-app approval rates, average approval and totals by location), with export to CSV. Associate-level results show with Employee Tracking on.
See LendPro with your own lenders
One application to the lenders configured for your stores, from a network of 18+ lenders and 25+ lending programs.