
LendPro is not a lender; the provider you choose makes the decision and sets the terms.
Key takeaways
- You fill out one application at a participating store, review the offers, then finish your chosen provider's full application and e-sign with the store.
- A pre-qualified amount is subject to the lender's final approval and is not a guarantee of approval.
- A lender may run a hard inquiry when you choose an offer and complete its full application.
- Lease-to-own is a rental-purchase agreement, not a loan, and the total cost is higher than the cash price.
What are the steps from finding a store to signing?
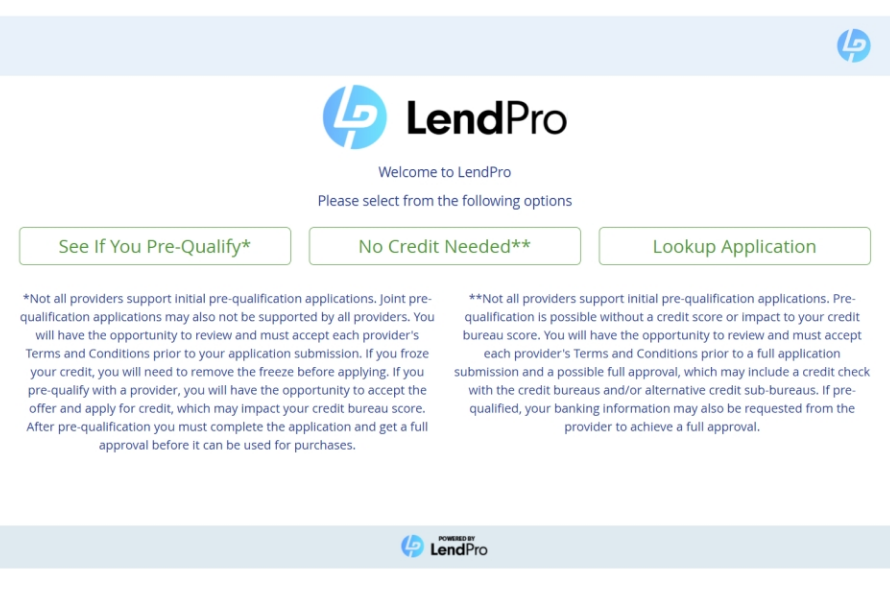
- Find a participating store. Look for See If You Pre-Qualify or No Credit Needed buttons on the store's website, a QR code or kiosk in the store, or ask an associate for a text link. You can also search by ZIP code with Find a store.
- Choose your path. See If You Pre-Qualify reaches the lenders the store works with. No Credit Needed goes straight to No Credit Needed providers.
- Fill out the short form once. One application reaches the providers in the store's lineup, so you do not apply to each one separately.
- Review your offers. Results show on screen once providers respond. Depending on the store, you may see offers from more than one provider side by side.
- Select an offer. You see that provider's confirmation with the available limit.
- Complete the provider's full application. It may ask for employment details and a debit card and/or bank account. Read and agree to the provider's terms, then submit.
- The store prepares your purchase. An associate creates the invoice for what you are buying.
- E-sign your agreement. Sign in the store or by a link sent by text or email.
- Delivery or pickup. The store arranges delivery or pickup and finalizes the sale with the provider.
Steps and screens vary by store and provider. Online and in-store lender availability, application requirements, and results may differ. Not every provider offers pre-qualification.
What does pre-qualified mean?
Pre-qualified means a lender has looked at the information you entered and shown an amount you may be able to finance. A pre-qualified amount is subject to the lender's final approval and is not a guarantee of approval. The lender makes its final decision after you complete its full application, and the final amount or terms can differ from what you first saw.
Pre-qualifying helps you shop with a budget in mind. You can compare offers before you commit to any of them, and you can walk away without choosing one.
Will checking my options affect my credit?
| Step | What usually happens |
|---|---|
| See If You Pre-Qualify | Where the provider supports pre-qualification, a soft pull that won't affect your credit score. |
| Choosing an offer and completing the full application | The lender may run a hard inquiry, which can appear on your credit report. |
| No Credit Needed | The provider's full application may include a check with the credit bureaus and/or alternative credit sources. |
| Providers without pre-qualification | Some providers do not offer a pre-qualification step. Read each provider's disclosures before you submit its application. |
Search by ZIP code and what you are shopping for. Pre-qualifying won't affect your credit score where the provider supports it.
What types of financing might I see?
Offers depend on the store, the purchase and your credit. In plain terms:
| Type | What it is | Who you pay |
|---|---|---|
| Loan | A lender pays for your purchase and you pay the lender back, with any interest and fees your agreement lists. | The lender |
| Installment loan | A loan you repay in set payments over a set number of months, so you know each payment and when the last one is due. | The lender |
| Lease-to-own | A rental-purchase agreement, not a loan. You rent the item through scheduled payments and can own it under the terms of your agreement. Total cost is higher than the cash price. | The lease provider |
Your offer screen and agreement name the provider and the type of agreement. Each provider sets its own terms.
What is No Credit Needed?
No Credit Needed is a path for shoppers with little or no credit history, or anyone who prefers to skip traditional lenders. It goes straight to No Credit Needed providers, where several offers may show side by side. No Credit Needed does not mean no review: the provider's full application may include a check with the credit bureaus and/or alternative credit sources, and it may ask about income and a bank account. Many No Credit Needed offers are lease-to-own.
How does lease-to-own work?
Lease-to-own is a rental-purchase agreement, not a loan. Total cost is higher than the cash price. With lease-to-own, the provider buys the item and you rent it through scheduled payments. Your agreement explains how and when you can own the item, and any early purchase option it offers. Lease-to-own generally covers goods, not labor or services.
Before you sign, find these in the agreement:
- Total cost. The full amount you pay if you make every payment, compared with the cash price.
- Payment schedule. The amount, how often and how many payments.
- Early purchase options. Whether you can own the item sooner and what that costs.
- Fees. Any processing, late or other fees.
- Who to contact. The lease provider services your agreement and takes your payments.
What happens if a lender declines me?
If one lender declines, offers from other lenders the store works with may still show, depending on how the store is set up. If you started with See If You Pre-Qualify and did not get an offer that works, you can try No Credit Needed. Questions about why a lender declined go to that lender, because it made the decision. See the shopper FAQ for more.
What should I check before I e-sign?
- The provider's name. This is who you will pay and who services your account.
- The amount and the item. Make sure the invoice matches what you are buying.
- The payment and term. Monthly or per-period payment and how many payments.
- The total cost. Rates, fees and, for lease-to-own, the total compared with the cash price.
- Delivery details. Confirm the date and any delivery terms with the store.
Can I apply for a higher amount later?
Yes, by starting a new application. Any new offer is subject to that provider's approval. To pick up an application you already started instead, use Lookup Application; see check your application.
Pre-qualified amounts are subject to the lender's final approval and are not a guarantee of approval. Not every provider offers pre-qualification. Lenders and lease providers make all decisions and set all terms; availability varies by store, state and purchase. Lease-to-own is a rental-purchase agreement, not a loan. Total cost is higher than the cash price.
Frequently asked questions
Is a pre-qualified amount the same as an approval?
No. A pre-qualified amount is subject to the lender's final approval. The lender decides after you complete its full application.
Will pre-qualifying hurt my credit score?
Where the provider supports pre-qualification, it uses a soft pull and won't affect your credit score. A lender may run a hard inquiry if you choose an offer and complete its full application.
What information does the full application ask for?
It depends on the provider. Many ask for employment details and a debit card and/or bank account information.
How do I sign my agreement?
After the store creates your invoice, you e-sign in the store or by a link sent by text or email.
Is lease-to-own a loan?
No. Lease-to-own is a rental-purchase agreement, not a loan. Total cost is higher than the cash price.
Do I have to accept an offer?
No. You can review your offers and choose not to continue. Nothing is final until you complete a provider's full application, agree to its terms and sign.
Who sets my rate and payments?
The lender or lease provider you choose. LendPro is not a lender and does not set terms.